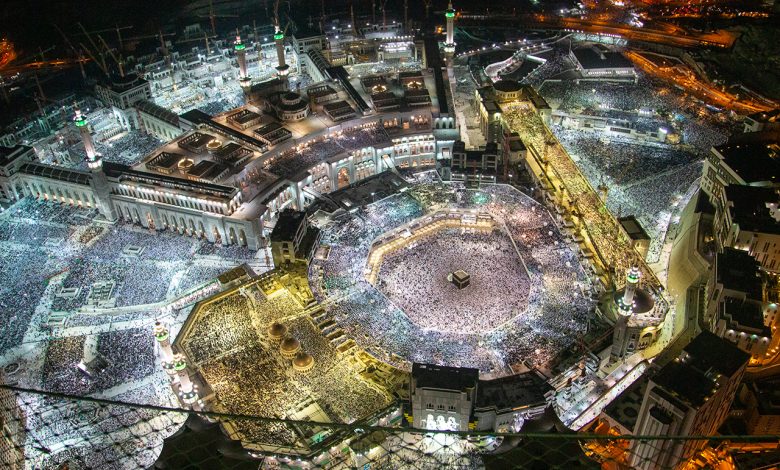
The big picture: Makkah’s real estate market is shifting from a model centered on selling land and units toward the development of income-generating assets, particularly hotels and serviced apartments. The shift is supported by improving occupancy rates and average room prices, especially during the Hajj and Umrah seasons, as well as by rising demand throughout the year
Why it matters: Hospitality is no longer a side business for Makkah’s real estate firms. It’s becoming their main engine. That means steadier, repeatable income, instead of one-off returns from selling plots or units.
Hotels Take the Lead
Financial and economic advisor Dr. Hussein Al-Attas said Makkah‘s hospitality sector is living through “one of its strongest historical phases.” He points to clear structural drivers. Umrah numbers keep rising. Hajj capacity keeps expanding. And Vision 2030 projects keep reshaping the city.
The Grand Mosque expansion helped. So did new rail and road links, plus a smoother visitor experience overall. Together, they lifted occupancy rates and average room prices, Al-Attas said. Demand is no longer confined to peak seasons, either. Year-round Umrah travel now brings hotels steadier bookings all year.
Jabal Omar Shows the Shift
Jabal Omar Development Company illustrates the trend well. The Makkah-based developer swung back to profit in Q2 2026. It posted a net profit of SAR 158.1 million ($42.2 million), reversing a SAR 42.1 million ($11.2 million) loss from a year earlier. Revenue jumped 42.5% to SAR 715.2 million ($190.7 million). The company credited stronger hotel performance during Hajj season, plus the opening of its Rotana property. Its hotel segment alone brought in SAR 1,339 million ($357.1 million) in H1 2026, up 17% year-on-year.
Khaled Al-Mubayyid, CEO of Manasat Real Estate, said Makkah holds a rare advantage: durable, structural demand. Steady pilgrim flows, combined with Vision 2030 targets, make hotels more attractive than many other property types. That’s especially true near the Grand Mosque and along new transport corridors. Developers, he added, now focus on operational quality, not just construction.
Policy is reinforcing that shift, too. Saudi Arabia’s new foreign ownership law took effect in January 2026. It opened parts of the real estate market to non-Saudi investors for the first time. That includes limited pathways into Makkah and Madinah for Muslim investors and foreign-owned Saudi firms. The goal: funnel fresh capital into hospitality assets like these.
By the numbers:
- SAR 715.2 million ($190.7 million): Jabal Omar’s Q2 2026 revenue, up 42.5% year-on-year
- SAR 158.1 million ($42.2 million): Jabal Omar’s Q2 2026 net profit, versus a SAR 42.1 million loss a year earlier
- SAR 1,454 million ($387.7 million): Jabal Omar’s total H1 2026 revenue, up 16% year-on-year
- 1,707,301: Pilgrims who performed Hajj in 2026, up roughly 2% from the previous year
- 92 million+: Umrah performers recorded in 2025 alone
- 268,000+: Licensed hotel rooms now operating in Makkah
- SAR 24 billion ($6.4 billion): Committed investment tied to the Rua Al Madinah hospitality pipeline, spanning more than 42,000 keys
- $29.02 billion: Estimated size of Saudi Arabia’s hospitality market in 2026, projected to reach $40.58 billion by 2031
Rising Supply Brings New Pressure
More rooms are coming, and that’s reshaping competition. Al-Attas expects new supply to squeeze prices modestly in some categories, at least short term. That’s especially true where new hotels cluster in the same tier. Still, he expects demand to absorb most of that capacity over time. Government targets keep pushing pilgrim numbers higher, year after year.
Al-Mubayyid agrees that room count alone won’t guarantee profitability. As competition intensifies, revenue per room will matter more than size. Developers also face real cost pressure: climbing land, construction and financing costs, high interest rates, and a shortage of trained hospitality staff. Together, these pressures could squeeze margins even as revenue grows.
What’s next: Looking ahead, both analysts see the same pattern taking hold. Makkah’s hotel story now hinges less on adding rooms, and more on how well developers run what they already own. Location, service quality and smart revenue management will decide who wins, they say, as supply and pilgrim demand keep expanding side by side.